.png)

Cross-border Spillovers of Monetary Policy
Monetary policy does not stop at national borders. Michael Patra explains how global spillovers test the RBI’s ability to chart its own course
Michael Patra is an economist, a career central banker, and a former RBI Deputy Governor who led monetary policy and helped shape India’s inflation targeting framework.
November 20, 2026 at 6:28 AM IST
There are external effects of the conduct of monetary policy that transcend national borders. This is particularly true of economies that are large, systemic and open. Their monetary policies tend to impact economic and financial conditions in other countries. These external effects are referred to as spillovers.
It is also observed that even small economies can generate external effects, especially in a crisis. They are rare and are referred to as spillbacks.
Some of them even use the Indian rupee as legal tender, as in Nepal. Instances of spillbacks were evident during the Asian crisis of 1997, the Latin American crisis of 1982 and the rouble crisis of 1998, which caused financial turbulence on Wall Street. The rouble crisis, for instance, acted as the "black swan" event that triggered the catastrophic collapse of Long-Term Capital Management (LTCM), a massive, highly leveraged US hedge fund.
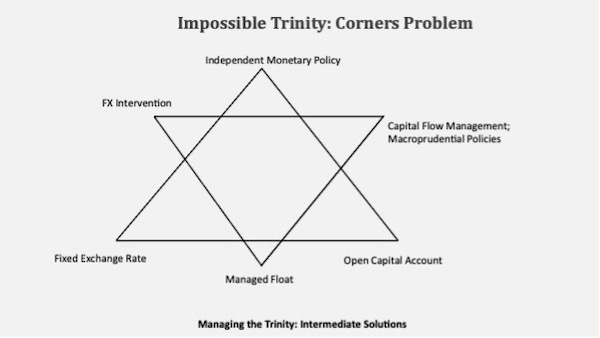
Every central bank conducting monetary policy faces the Impossible Trinity or Policy Trilemma. It is an economic principle stating that a country cannot simultaneously maintain a fixed exchange rate, an open capital account, and an independent monetary policy. A nation can choose at most two of these three objectives, with the third becoming impossible to achieve.
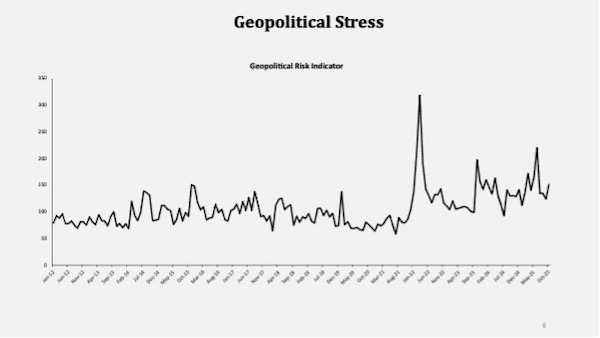
Geopolitical Stress
About 15% of global maritime trade volume normally passes through the Suez Canal, while a fifth of the world’s crude oil supplies and liquefied natural gas passes through the Strait of Hormuz.
Trade Policy Uncertainty
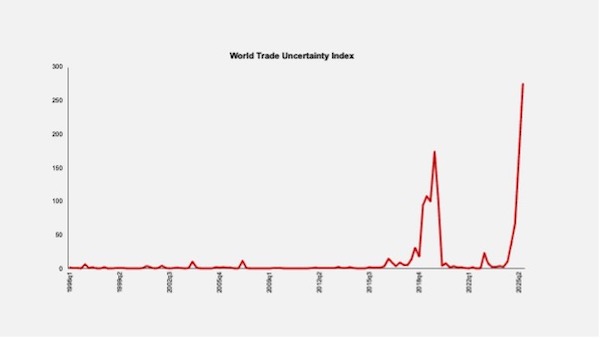
The Trade Policy Uncertainty Index (TPUI) is a monthly index that is constructed by counting the frequency of joint occurrences of trade policy and uncertainty terms across major newspapers.
Since 2023, the TPU index has been spiking several times in response to heightened tensions between the US and its trading partners, notably China.
Overall Economic Policy Uncertainty
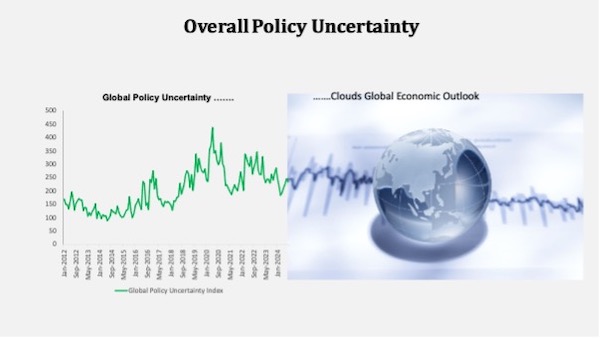
The Global Economic Policy Uncertainty (GEPU) Index is a GDP-weighted average of national EPU indices for 21 countries representing about 71% of global output on a PPP-adjusted basis and roughly 80% at market exchange rates.
A text mining-based economic policy uncertainty index constructed for India uses internet search data from Google Trends. In the case of advanced economies such as the US, uncertainty shocks lead to lower output and lower prices. In the Indian context, however, uncertainty shocks lead to slower growth but higher inflation.
This presents a dilemma for monetary policy: tighten to control high inflation or ease to respond to lower growth? Again, this reiterates the importance of country-specific assessment.
Financial Market Volatility
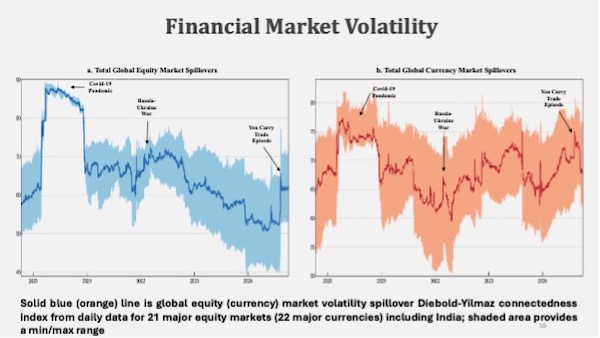
On a net basis, emerging economies tend to be at the receiving end of spillovers.
Supply Chain Pressures
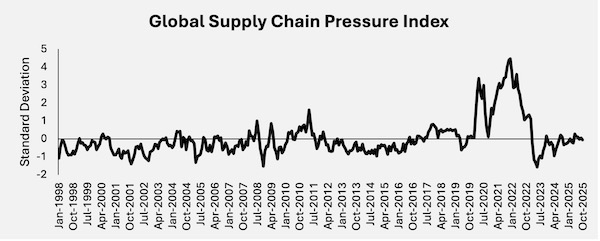
Reordering of global supply chains is being driven by aiming for resilience in the face of geopolitical risks, - from "just-in-time" to "just-in-case", diversifying suppliers, adopting regional and compatible sourcing strategies, control over strategic materials and technology, and increasing inventory. Technologies like digitalisation and automation are playing a role in enabling this adaptation.
Against this backdrop, central banks have to maintain a close vigil on global events to (a) identify periods of stress; (b) assess the intensity and duration of stress in the financial system; and (c) gauge the ability of financial markets and intermediaries to withstand shocks and imbalances. End
This is Part 16 of the Masterclass with Michael Patra.
Masterclass with Michael Patra: Previous Sessions
Part 1
Origins, Ideas and Institutions
Michael Patra begins the masterclass by tracing how central banks evolved from fragile monetary experiments into institutions entrusted with preserving trust, stability and confidence.
Part 2
RBI and the Safeguarding of Confidence
The series then turns to the RBI’s evolution, its expanding institutional role, and the balance between autonomy, growth and price stability.
Part 3
The Rise and Fall of Monetary Policy Regimes
From Bretton Woods to monetary targeting, the masterclass examines how central banks repeatedly reinvented monetary policy frameworks when old anchors collapsed.
Part 4
When Monetary Anchors Collapse
As monetary targeting broke down globally, central banks were pushed again into uncertainty, instability and regime change.
Part 5
Central Banking and Monetary Policy Regimes: The Indian Experience
How India’s trysts with crises, policy responses and changing gears in the development strategy imposed monetary policy regime shifts upon the RBI.
Part 6
Inflation Targeting and the Contract of Trust
From time inconsistency to flexible mandates, Michael Patra explains how inflation targeting became the world’s most durable monetary policy regime.
Part 7
India: Survival of the FITtest
From the Urjit Patel committee to the first MPC, Michael Patra traces how India designed, legislated and launched flexible inflation targeting.
Part 8
Lessons From India’s Inflation Targeting Decade
After a decade tested by a pandemic and war, Michael Patra distils four lessons from India’s flexible inflation-targeting framework.
Part 9
The Plumbing in the Monetary Policy Architecture
Patra explains the plumbing of monetary policy, tracing how RBI liquidity management transmits the MPC’s repo rate through banks and money markets.
Part 10
How the RBI Manages Liquidity, From the LAF Corridor to Sterilisation and Beyond
Michael Patra explains how the RBI manages liquidity, from sterilisation and CRR operations to forecasting and the LAF corridor’s role in transmission.
Part 11
The Pipes: Monetary Policy Transmission
Setting the repo rate is only the start. Michael Patra explains how monetary policy reaches the economy and what gets lost along the way.
Part 12
Operational Realities in Monetary Policy Transmission
Monetary policy transmission begins instantly in money markets, but frictions across rates, bonds and bank credit weaken its speed and strength.
Part 13
International Dimensions of Monetary Policy
How exchange rate regimes shape monetary policy independence and why global forces constrain domestic policy choices.
Part 14
The Forces That Set Exchange Rates and the Regimes of the Rupee
Patra explains the underlying principles of exchange rates, how they shape the economy, and how the rupee has undergone regime shifts.
Part 15
Why the RBI Cannot Leave the Rupee to Market Forces
Why does the RBI intervene at all? Despite being the world’s fifth-largest reserve holder, its gross foreign liabilities exceed its reserves quite substantially, by over 10% of GDP. And then there is this growth angle too.
More From BasisPoint