.png)

Asian Markets Rise as US Futures Rebound
Here’s your quick read to start the day: a chatty, no-fuss look at overnight moves, the big story, what’s on the docket, and the tickers you need to watch.
November 13, 2026 at 2:17 AM IST
Global Mood: Cautiously risk-on
Asian markets were mostly higher on Friday, led by South Korea’s Kospi, which gained 2.6%. Japan’s Nikkei 225 rose 1.46%, while Australia’s S&P/ASX 200 fell 0.79%. US equity futures advanced, with Nasdaq-100 futures up 0.6%, S&P 500 futures gaining 0.4% and Dow futures rising 0.3%.
Wall Street ended lower on Thursday, with the Nasdaq Composite and S&P 500 falling around 0.4% each, as Nvidia’s 4.3% decline weighed on major indices. Nvidia founder and CEO Jensen Huang stepped down, with CFO Colette Kress taking over as interim CEO. Rising oil prices also pressured sentiment, with Brent crude settling 3% higher at $95.82 a barrel after US President Donald Trump ruled out the need for a deal with Iran. Investors await US producer price data for October. The GIFT Nifty was trading at 25,265.5, down 35.5 points, or 0.14%, pointing to a mildly negative opening for Indian equities.
THE BIG STORY
Four oil tankers were struck by explosions in the Strait of Hormuz on Wednesday and Thursday, according to Iran's military, which said the vessels had ignored warnings and entered restricted areas. Iran's Revolutionary Guards Navy said two super tankers hit naval mines on Wednesday, while two other tankers caught fire on Thursday. Reuters could not independently verify Iran's account.
The attacks come despite hopes of de-escalation in the US-Iran war and a recovery in shipping traffic through the strategic waterway. At least 10 ships were attacked in the first 10 days of November, following 37 attacks in October, the highest monthly tally since the conflict began in February. The UK Maritime Trade Operations agency also reported a vessel being struck by an unidentified projectile near the UAE's Ras Al-Khaimah.
Russian President Vladimir Putin agreed to allow European representatives to join the next round of Ukraine peace talks, according to US envoy Steve Witkoff, potentially broadening diplomatic efforts to end the war. Putin said Russia remained open to dialogue with Europe but warned that deploying Western troops in Ukraine after a peace agreement would trigger a resumption of hostilities.
Ukrainian President Volodymyr Zelenskiy welcomed the prospect of European participation and said future discussions should focus on ceasefire arrangements and de-escalation. The latest diplomatic push follows two days of US-mediated talks in Abu Dhabi, the first direct negotiations between Russia and Ukraine in nine months. Major differences remain over territorial demands, particularly Moscow's insistence on taking full control of the Donbas region.
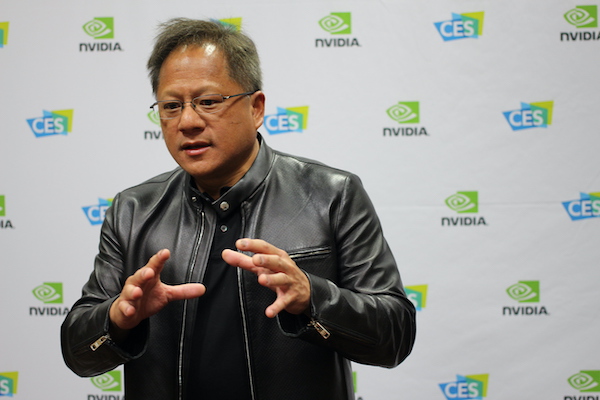
Nvidia CEO Jensen Huang resigned on Thursday following revelations of extramarital relationships, including one involving a company employee, plunging the chipmaker into a leadership crisis and raising questions over its influence on US-China technology policy. Chief Financial Officer Colette Kress will serve as interim CEO while the company considers internal and external candidates for a permanent successor.
Nvidia shares fell 4.3% on Thursday, while rivals AMD and Broadcom gained around 6% each. Huang's departure raises concerns over leadership continuity and execution at a company central to the global artificial intelligence boom.
Data Spotlight
US existing home sales fell 5.5% month-on-month to an annualised rate of 3.75 million units in October, the lowest level since August 2010 and below market expectations of 3.85 million. Sales declined across most regions, led by a 9.7% drop in the West and a 6.5% fall in the South, while the Northeast was unchanged. Housing inventory rose 1.3% from September and 4.6% year-on-year to 1.59 million homes, equivalent to 5.1 months of supply, up from 4.7 months. The median home price increased 0.4% from a year earlier to $416,700. Elevated mortgage rates continued to weigh on affordability and demand.
US initial jobless claims increased by 9,000 to 200,000 in the week ended November 7, slightly exceeding the consensus estimate of 195,000. However, claims remained low by historical standards. Continuing claims fell by 13,000 to 1.679 million in the week ended October 31, their lowest level since March 2023. Claims filed by federal employees rose by 33 to 585, keeping attention on the impact of the administration's efforts to reduce the public-sector workforce. Overall, the data continued to indicate resilience in the US labour market.
The average US 30-year fixed mortgage rate declined by 7 basis points to 7.11% in the week ended November 12, marking a fourth consecutive weekly fall and a seven-week low. The 15-year fixed mortgage rate also eased to 6.45% from 6.57% a week earlier. However, borrowing costs remain well above year-ago levels, when the 30-year rate averaged 6.24%, continuing to constrain housing affordability.
Takeaway: The US housing market remains under pressure from elevated borrowing costs, with existing home sales falling to their lowest level since August 2010. Recent declines in mortgage rates could provide some relief, although borrowing costs remain well above year-ago levels. Meanwhile, low initial jobless claims and falling continuing claims point to continued resilience in the labour market, giving the Federal Reserve limited reason to ease policy aggressively on employment concerns alone.
WHAT HAPPENED OVERNIGHT
US Stocks Close Lower as Nvidia Selloff Offsets Energy Gains
- The Dow Jones Industrial Average fell 0.36% to 52,297.09, the S&P 500 declined 0.35% to 7,592.40, and the Nasdaq Composite lost 0.39% to 25,366.09 on Thursday.
- Nvidia shares dropped 4.3% following CEO Jensen Huang's reported exit, although they recovered from an earlier decline of nearly 12%, weighing on technology stocks.
- The S&P 500 energy sector rose 1.5%, leading gains among major sectors for a fourth consecutive session, supported by higher crude oil prices.
- Other AI-linked stocks also weakened, with Nebius tumbling 16.8% after its earnings and outlook, while CoreWeave fell 6.9%. However, Broadcom, AMD and Alphabet gained.
- Investors now await Friday's US Producer Price Index data for further clues on inflation and the Fed's monetary policy outlook.
US Dollar Holds Near 103 as Hawkish Fed Remarks and Hot Inflation Fuel Rate Bets
- The US dollar index hovered just below 103 on Thursday after gaining more than 1% over the previous two sessions, reaching its highest level since April 2025.
- Stronger-than-expected October inflation data and hawkish comments from Federal Reserve officials reinforced expectations of further monetary tightening.
- Fed Governor Christopher Waller said a 50-basis-point hike in December may be necessary if inflation continues to accelerate, while Dallas Fed President Lorie Logan backed at least two additional 25-basis-point increases.
- Markets are pricing in a 91% probability of a rate hike next month, with further increases in January and potentially April also being factored in.
- Investors now await US initial jobless claims and existing home sales data for further cues on the economy and the Fed's policy outlook.
US 10-Year Treasury Yield Climbs Above 5.05% as Markets Price Further Fed Rate Hikes
- The 10-year US Treasury yield rose above 5.05% on Thursday, reaching a three-week high as stronger-than-expected October inflation data reinforced expectations of further Federal Reserve rate hikes.
- Both headline and core consumer prices rose more than expected in October, suggesting higher energy costs linked to the Iran war were feeding into broader inflation.
- Treasury yields across the belly of the curve also climbed amid concerns over Nvidia CEO Jensen Huang's reported departure and potential disruption in the AI sector's debt financing.
- Fears that a slowdown in AI-related corporate credit activity could trigger broader fixed-income selling added to pressure on Treasury markets.
Oil Rises 3% as Attacks on Saudi Energy Infrastructure and Hormuz Disruptions Raise Supply Fears
- Brent crude rose $3.06, or 3.3%, to settle at $95.82 a barrel on Thursday, while WTI gained $2.21, or 2.6%, to $88.74.
- Prices rebounded after Yemen's Iran-aligned Houthis claimed attacks on Saudi Arabia's East-West oil pipeline, a pumping station in Yanbu, and an Aramco building in Riyadh.
- Iran's military also said four oil tankers were hit by explosions in the Strait of Hormuz, raising concerns over disruptions to a waterway that carried nearly a fifth of global crude supplies before the war.
- US President Donald Trump said Washington did not need a deal with Iran, dampening hopes of a diplomatic resolution.
- Ukraine continued attacks on Russian energy infrastructure, with drones striking the Baltic port of Ust-Luga and damaging fuel storage facilities.
- However, gains were limited by rising US crude, gasoline and distillate inventories, while OPEC+ data showed higher crude production in October, led by Saudi Arabia.
- Both Brent and WTI remained down around 2.5% for the week.
Day’s Ledger*
Economic Data
- India Weekly Forex Reserves
- German October WPI
- Eurozone September Trade Balance
- Eurozone July-September GDP
- US October PPI
Policy
- ECB's Elderson Speaks
- ECB's Schnabel Speaks
- EU Leaders Summit
- US Fed Collins Speaks
- US Fed Logan Speaks
- US FOMC Member Bowman Speaks
- German Buba President Nagel Speaks
- US FOMC Member Daly Speaks
Corporate Actions
- Earnings: Ballarpur Industries, Edelweiss Financial Services, MTNL
Tickers to Watch
- OIL INDIA July-September 2026 net profit down 21.3% QoQ to 22.594 billion rupees from 28.702 billion rupees. Revenue up 1.4% to 80.712 billion rupees. EBITDA down 26.5% to 30.01 billion rupees. Margin at 37.2% vs 51.3%. Interim dividend of 7 rupees/share, payable by December 12, 2026.
- OLA ELECTRIC MOBILITY July-September 2026 revenue down 39% YoY to 4.21 billion rupees from 6.9 billion rupees. Net loss narrows to 3.62 billion rupees from 4.18 billion rupees. EBITDA loss widens to 2.18 billion rupees from 2.03 billion rupees. Gross margin at 29.93% vs 30.9%. Operating expenses fall to 3.69 billion rupees from 4.72 billion rupees.
- HITACHI ENERGY July-September 2026 net profit up 20.8% YoY to 3.19 billion rupees. Misses the 3.45-billion-rupee estimate. Revenue up 63.6% to 29.965 billion rupees. Beats the 25.88-billion-rupee estimate. EBITDA up 36.4% to 4.063 billion rupees. Misses the 4.38-billion-rupee estimate. Margin at 13.6% vs 16.3%, below the 17% estimate.
- RELIANCE INDUSTRIES gets Ministry of Power approval to lay an overhead transmission line in Gujarat's Bharuch district for 25 years. Subject to statutory clearances.
- MAHINDRA & MAHINDRA October 2026 production is up 30.44% YoY to 1.24 lakh units. Sales up 7.3% to 1.27 lakh units. Exports up 77.5% to 7,241 units from 4,079 units.
- VODAFONE IDEA reported a loss of 59.75 billion rupees for July-September 2026, compared to a loss of 37.47 billion rupees in April-June 2026. Includes an exceptional loss of 4.62 billion rupees, against a 16.11 billion rupee gain earlier. Revenue up 1.7% QoQ to 118.84 billion rupees.
- IRCTC July-September 2026 net profit down 22.9% YoY to 2.636 billion rupees. Revenue up 16.3% to 13.331 billion rupees. EBITDA up 1% to 4.08 billion rupees. Margin at 30.6% vs 35.2%. Catering up 26.05% to 6.55 billion rupees. Tourism up 28.42% to 1.92 billion rupees. Rail Neer up 7.5% to 1.011 billion rupees. Internet ticketing up 1.01% to 3.898 billion rupees.
- When to Fight, When to Talk, And When to Stop
- America's 2032 Social Security Cliff Could Carry Wider Costs for India
- India’s Poverty Success Story Needs a Second Look
- Record SIPs Won't Guarantee Record Profits for AMCs
- Rural Energy Must Deliver More Than Connections
- Gold’s Shine Fades, but its Foundations Hold
- Nearly 70% of PLI scheme segments on track, says NITI Aayog report
- FISME seeks sectoral export studies, testing overhaul to boost MSME trade
- India's festive online sales rise 17%, but shoppers spend less per order
- India's Gulf oil imports surpass Russia for first time since Iran war
- Costco eyes broader India tech footprint as AI bets grow
- GAIL, farm cooperative sign pact to explore $1.6 billion Andhra Pradesh urea project
- India's Reliance plans $4.6 billion coal-to-gas project, document shows
- Codelco, Adani Group sign pact for copper exploration project
(*Compiled from various media sources)
See you tomorrow with another edition of The Morning Edge.
Have a great trading day
More From BasisPoint