Global copper prices have risen to record highs recently, and this should generally be bad news for Indian consumers, and a boon for refiners.
What is ironic, however, is that even with prices soaring around 50% in the past year to an all-time high above $14,800 per tonne this month, processors are suffering huge losses. And this is because despite the country’s ambition to build massive smelting capacity to process ore, the supply from domestic mines is only a fraction of the raw material requirement.
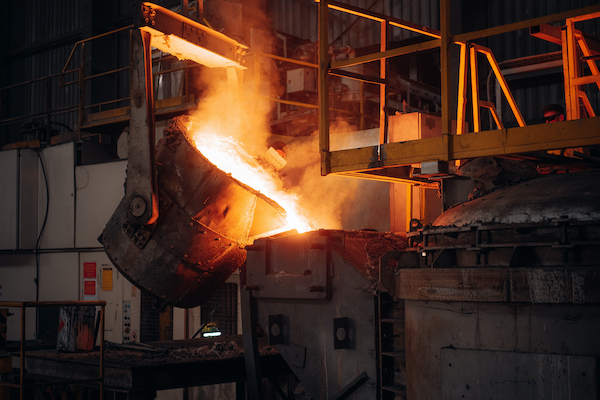
Over the last few years, smelters and refiners have upped capacity to prepare for rising demand from sectors such as electric vehicles, data centres, and renewable energy, as well as for grid expansion. While the high prices may give the impression that it was a good strategy, there have been challenges in the form of a unique fee, called treatment and refining charges, or TC/RCs.
A smelter traditionally purchases copper concentrate - a semi-processed ore containing about one-third pure copper - from miners at a price based on copper rates on the London Metal Exchange after deducting treatment and refining charges. TC/RCs keep changing with supply and demand. When the material is plentiful, smelters make good money, but when it’s scarce, these charges fall and profit margins shrink.
China’s expansion of smelting capacity, combined with disruptions at some major mines created a supply squeeze such that the TC/RC rate for 2026 fell to zero for the first time, while spot charges plunged deep into negative territory.
In a negative charge scenario, smelters effectively give up their processing margin, and in extreme cases, pay to secure concentrates to keep their plants running. That’s the situation now, with the Indian Primary Copper Producers Association saying charges faced by some local buyers had fallen to as low as minus $1,300 per tonne, from $300-$400 a tonne earlier. Although the figures measure different things -- an annual benchmark used for long-term contracts, spot rates and charges reported by the industry group for some Indian buyers -- they all point in the same direction.
In such a situation, the strategy of boosting capacity based largely on imported concentrate warrants closer scrutiny. When India planned to boost its processing capacity, the economics of imported material looked different, but the reality is vastly different now.
The decline in TC/RCs was partly caused by China accounting for more than 90% of the growth in global copper smelting since 2005, boosting its share from just 15% to about 50% by 2025, according to the International Energy Agency. The current mine projects point to a tighter copper concentrate market. Globally, furnaces were built faster than exploring new viable mines or increasing production at existing sites. Hindustan Copper, the country’s only integrated producer with operating mines, has been trying to triple its mining capacity to 12.2 million tonnes, but the target has been pushed back from 2028-29 to 2030-31.
On the other hand, India’s installed production capacity rose 64% from 2023-24 to around 1.3 million tonnes in 2025-26, with Hindalco and Vedanta operating established copper plants and the Adani group adding a new mega smelter in Gujarat. Adani’s $1.2 billion plant, designed to be one of the world’s largest single-location copper smelters with an initial capacity of 500,000 tonnes a year, produced just 94,000 tons between April 2025 and February 2026, according to Bloomberg. The plant annually needs about 1.6 million tonnes of copper concentrate to run at full capacity, but Bloomberg’s analysis of import records showed it had bought just over a quarter of that requirement between February 2024 and February 2026. Adani, however, said it had long-term concentrate supply tie-ups to fully meet its operational needs. The facility also imported more than 26,400 tonnes of copper anodes, a semi-refined form of the metal, over the past two years, according to Bloomberg analysis.
The numbers paint a somewhat bleak picture. India’s copper consumption rose 9% in a year to almost 2 million tonnes in 2024-25, whereas local mine output was equivalent to only 25,000 tonnes of the metal in the year to March 2025. The country imports more than 90% of its concentrate requirements, despite having substantial underground resources. India has about 1.66 billion tonnes of copper ore, but only about 164 million tonnes are classified as reserves, according to Hindustan Copper. India built plants but paid less attention to what feeds them.
Although smelters have some cushion -- they also produce gold, silver and sulphuric acid as by-products -- that safety net is not sustainable.
Massive investments in downstream projects should not, however, be seen as a mistake. Mines take years, sometimes more than a decade, to develop and a country expecting demand to surge can’t keep waiting for domestic ore before building the rest of the chain. However, the two aspects have remained disconnected for so long that a global shock exposed the vulnerability of the policy. The issue is not whether smelters should have been built, but whether long-term supply arrangements, stakes in overseas mines and domestic exploration kept pace with the expansion in processing capacity. Indian companies are now looking at stakes in foreign copper mines, while the government is paying more attention to local mining.
It’s neither realistic nor necessary for India to become self-sufficient in copper concentrate. What it really needs is raw material security through diversified sources, long-term supply contracts with overseas mines, higher domestic ore production and increased recycling. That would reduce the risk that problems at any single mine, disruption in shipping routes or trade policy changes abroad can dictate the cost and availability of copper concentrates for Indian smelters. The recent surge in global prices was driven in part by expectations that the US would impose tariffs on copper. That prompted traders and industrial buyers to build inventories in the US, resulting in shortages elsewhere. The episode demonstrated the vulnerability of depending too much on foreign markets.
India is unlikely to eliminate copper concentrate imports because local mine production and economically viable reserves are not sufficient to meet its needs, but better supply arrangements and stronger recycling could reduce the pain. Imports should be part of a solution, rather than the foundation of the country’s copper strategy.
Historically high copper prices may have looked like an endorsement of India’s policy direction, but the collapse in TC/RCs and the sharp price swings caused by US tariff speculation point to a different lesson: The strategic asset is not the furnace, but secured supplies of the material that keeps the furnace running.
.png)